Mortgage Broker Resume Examples: the lines they read
Create a Mortgage Broker Resume That Shows Volume and Lender Depth
By Mustafa Tarabya, founder of CVBooster · Published · Updated
Mortgage broker resume example, keyword list and writing guide covering funded volume, lender panels, NMLS licensing, referral pipeline and loan products.
Sample resumes for a mortgage broker
The same mortgage broker content laid out in three CVBooster templates, so you can see what the finished document looks like before you write a word.
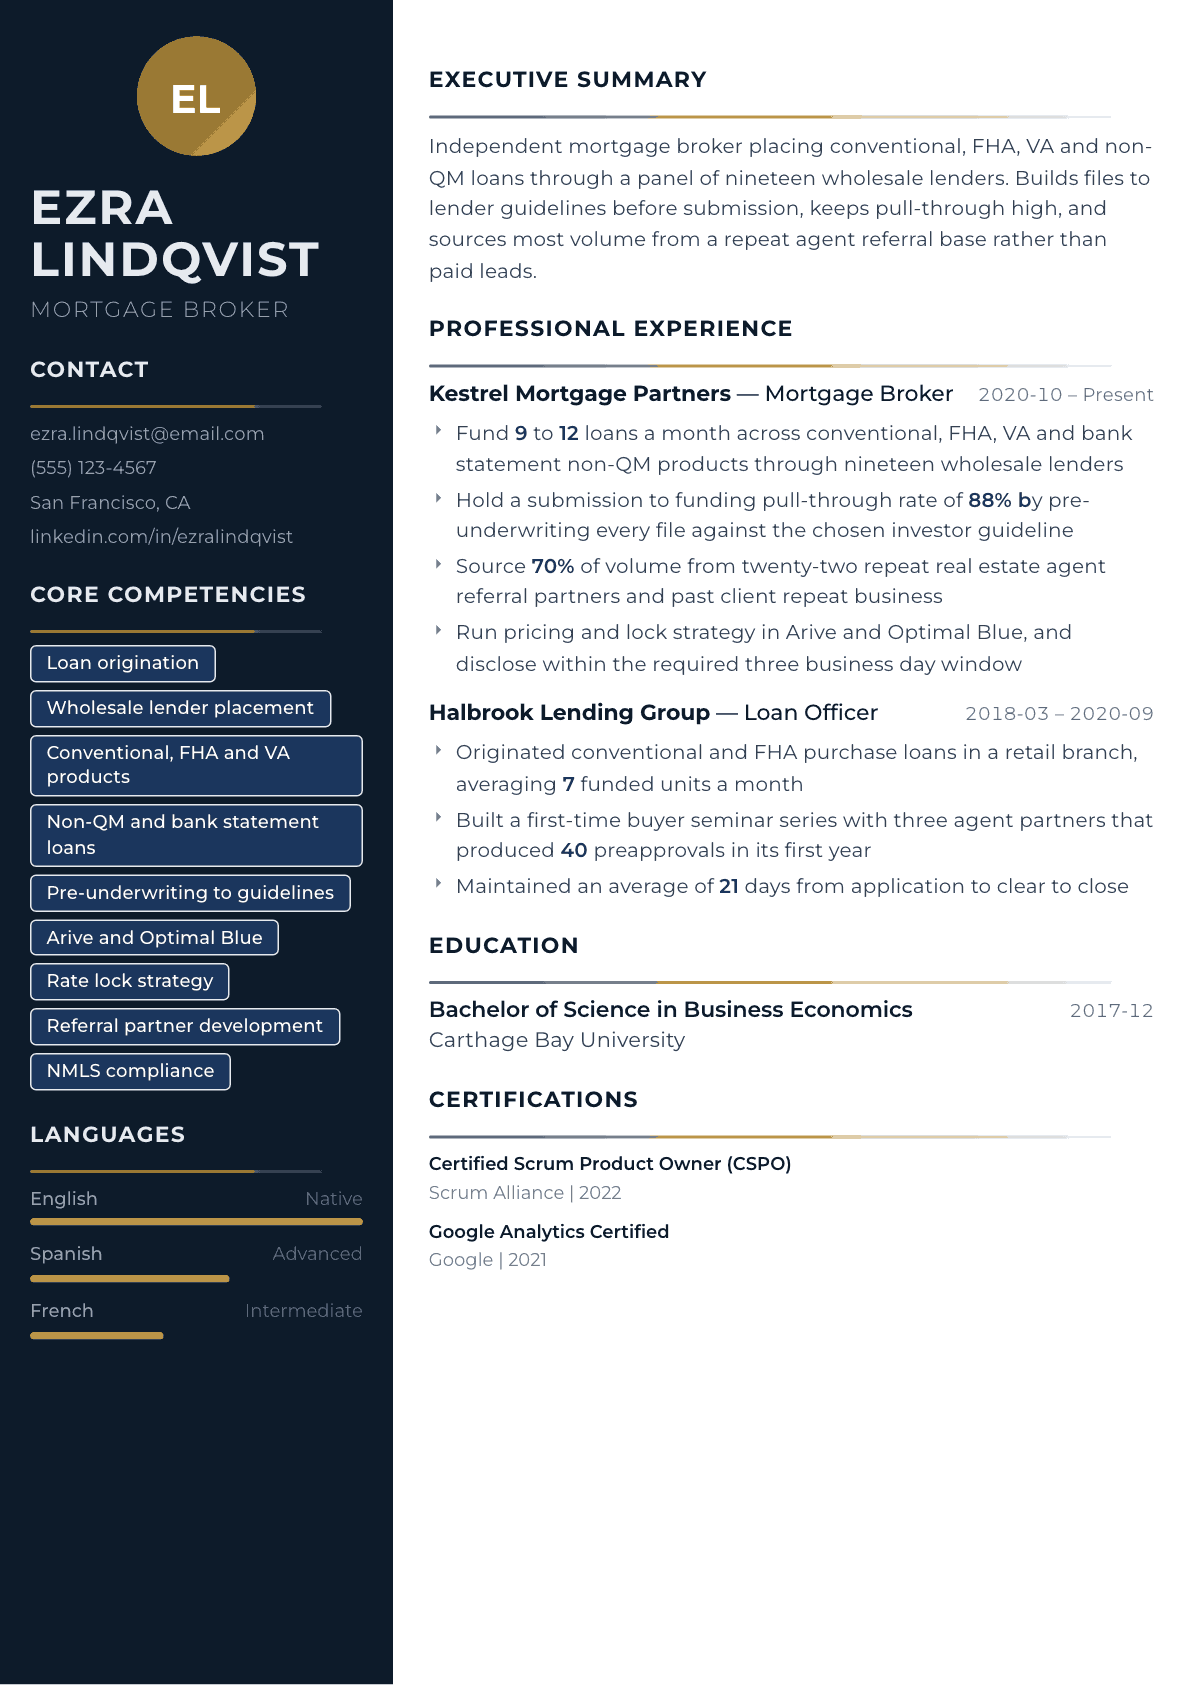
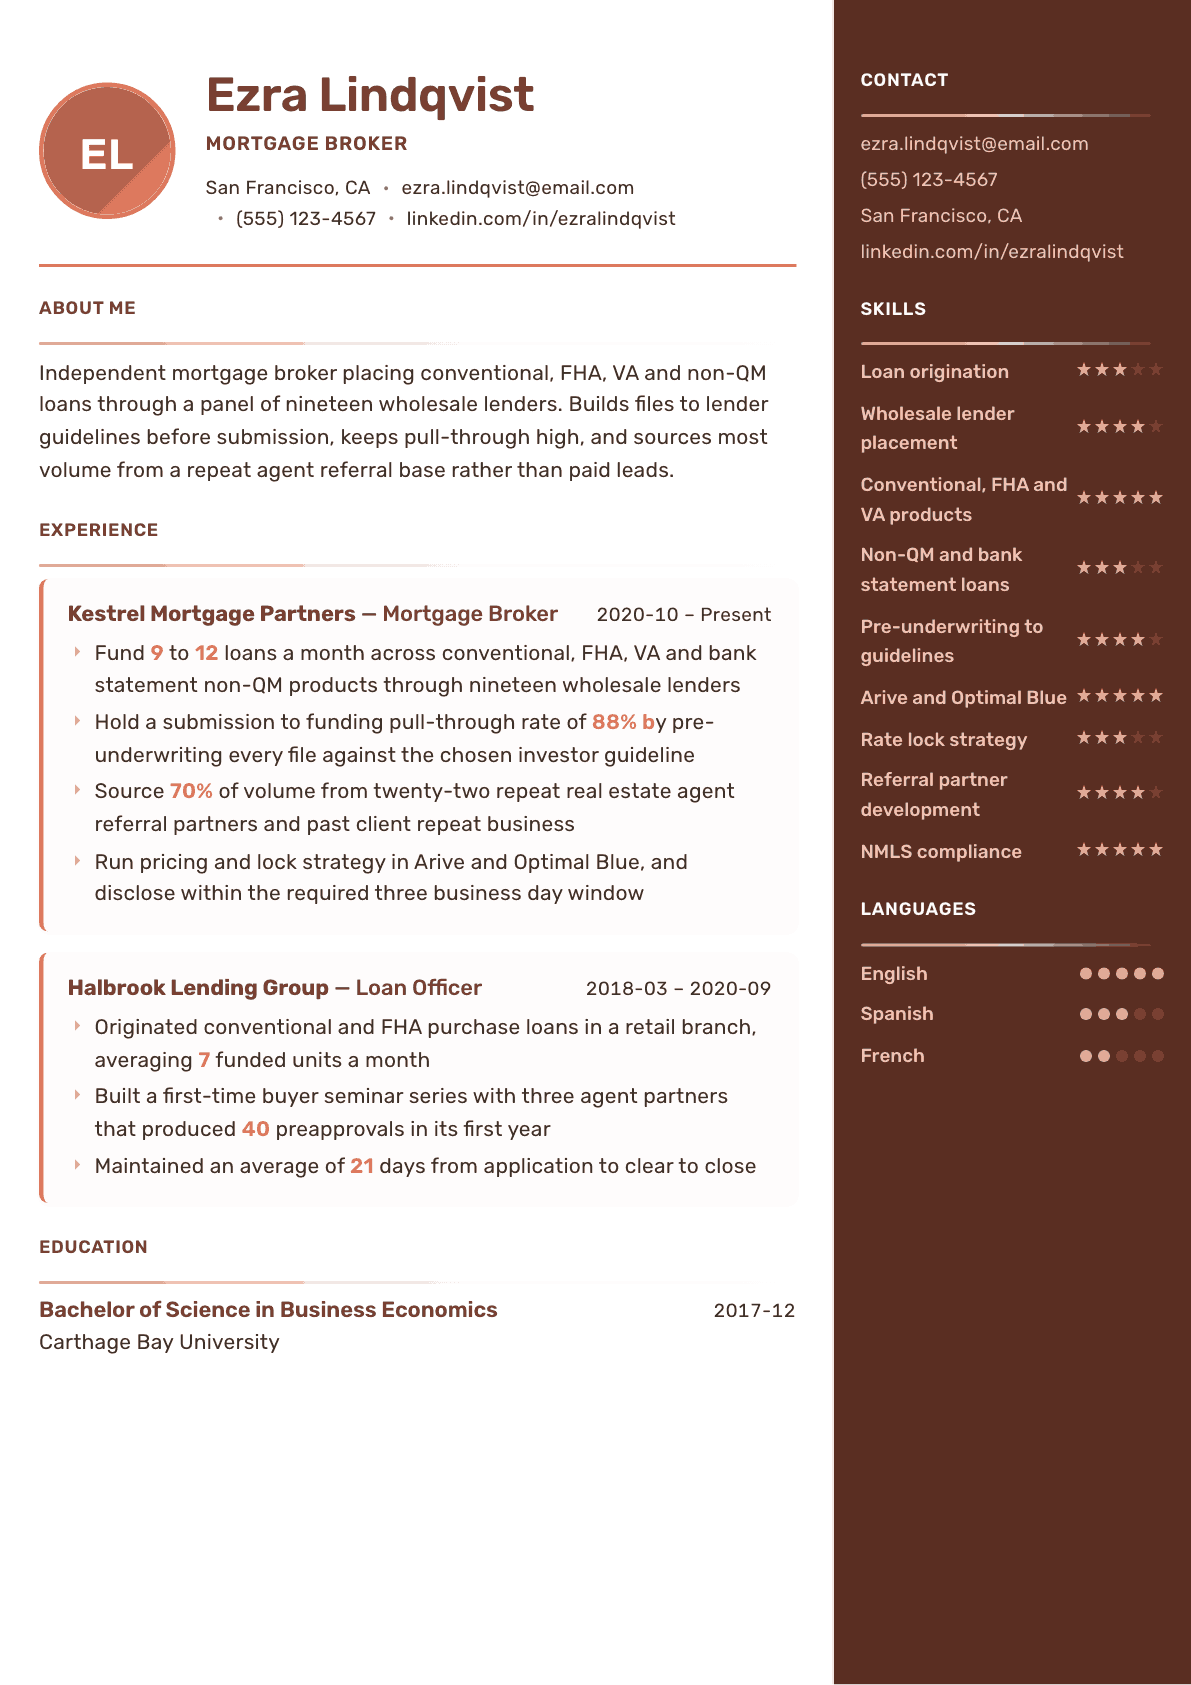
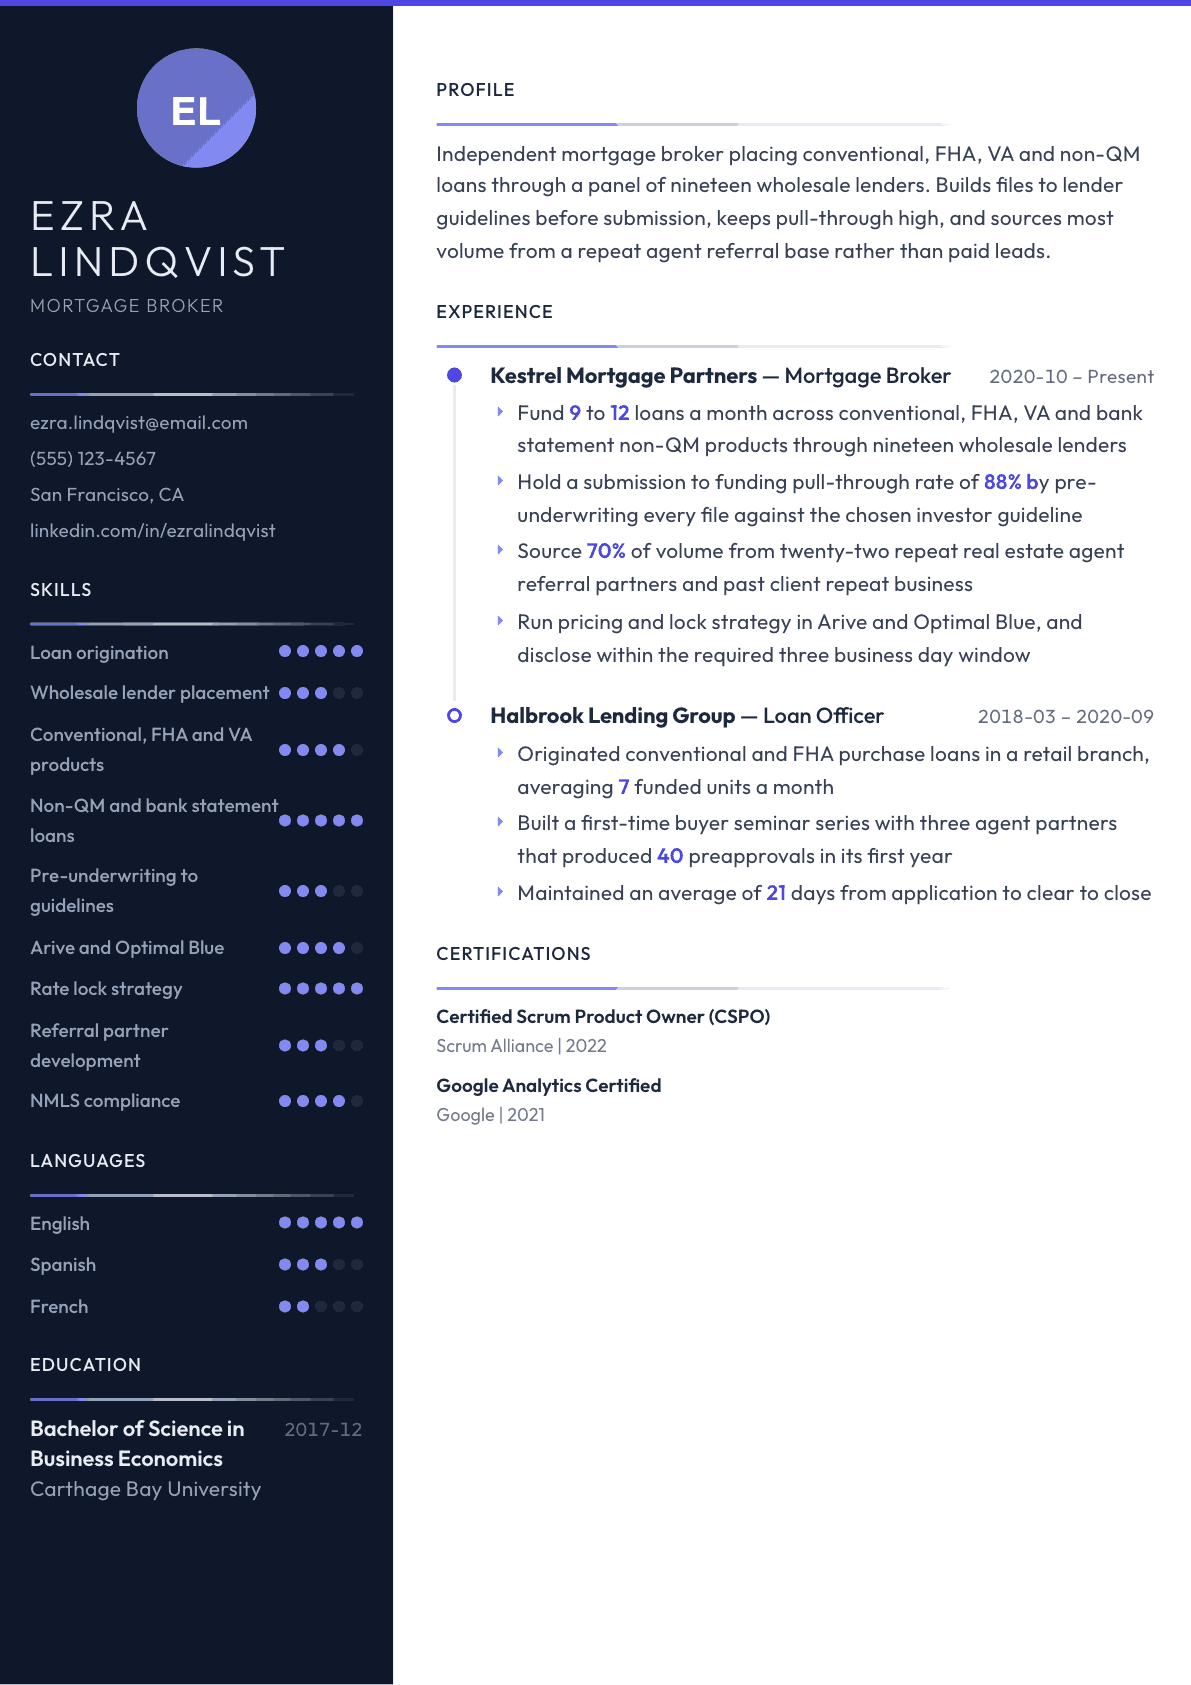
Example Mortgage Broker summary
Licensed mortgage broker with seven years in origination, funding nine to twelve loans a month through a panel of nineteen wholesale lenders across conventional, FHA, VA and non-QM programs. Pre-underwrites every file to the investor guideline and keeps pull-through near ninety. Draws most volume from repeat agent partners rather than paid leads. Works Arive and Optimal Blue daily.
Skills to list on a Mortgage Broker resume
- Mortgage loan origination
- Wholesale lender relationships
- Conventional and jumbo loans
- FHA and VA lending
- Non-QM and bank statement programs
- Investor DSCR loans
- Pre-underwriting and file structuring
- Credit and income analysis
- Rate lock and pricing strategy
- Arive and LendingPad
- Encompass
- Optimal Blue
- TRID disclosure timing
- Referral partner development
- NMLS licensing and continuing education
What actually gets this resume read
- Put your NMLS number and the states you are licensed in at the top, because no lender reads further without it.
- Give funded units per month and annual volume, and say whether it is purchase heavy or refinance heavy.
- Name the wholesale lenders on your panel by count and describe the niches you can place, such as non-QM or jumbo.
- Report pull-through from submission to funding, since that number separates a broker from a lead collector.
- Say where your business comes from: agent referrals, past clients, builders, financial planners or paid leads.
- List the origination and pricing platforms you use, such as Arive, Encompass, LendingPad or Optimal Blue.
- Show compliance discipline: disclosure timing, changed circumstance handling and how you document borrower contact.
How to write a mortgage broker resume
A mortgage broker resume has an unusual reader. It might be a brokerage owner recruiting producers, a wholesale account executive evaluating a partner, or a bank hiring you back into retail. All three start at the same place: your license status, your funded volume, and where the business comes from when the market turns.
The weak version of this resume is a sales biography. It talks about relationships, dedication and putting clients first, and never states units funded, pull-through, or the lender panel behind the placements. A broker who cannot quantify production is asking to be paid on faith.
This guide covers the licensing header, how to write production honestly across a mixed purchase and refinance cycle, how to describe lender depth and niche placement, how to show pre-underwriting discipline, and how to present a referral network as an asset rather than a claim.
Format: license header, production block, then the story
One page for most brokers, two only if you carry a management or branch build history alongside personal production. The reader is scanning for numbers and licenses, and prose slows them down.
Put the licensing line directly under your name. Your identifier under the nationwide licensing system and the states you are authorized in decide whether the rest of the resume is relevant at all, since state coverage is often the reason a specific opening exists.
- Header: name, city and state, phone, email, loan originator identifier, and every state you are licensed in.
- Production block right under the summary: funded units per month, annual volume, purchase and refinance split.
- Sections after that: experience, lender panel and product niches, systems, referral sources, education, designations.
- Give each brokerage or branch its own line stating whether you originated only or also managed other originators.
Production: units, mix and the cycle you produced in
Lead with funded units per month rather than annual dollars, because units are comparable across markets and price points. Add annual volume second, and give the purchase to refinance split, since a producer whose book was mostly refinance in a falling rate cycle is describing a different skill from one selling purchase business.
Show more than one year. A single strong year invites the suspicion that it was a rate window rather than a pipeline, and two or three years of production, even declining, reads as honest and durable.
Pull-through is the number most brokers omit and the one owners care about. Submissions that reach funding measure whether you structure files correctly at intake, and a high figure means the processing team is not doing rework on your behalf.
Lender panel and product depth
A broker's value is placement. State how many wholesale lenders you are approved with, and more importantly, name the product categories you can actually place: conventional agency, government including FHA and VA, jumbo, bank statement and profit and loss programs, investor debt service coverage loans, non-warrantable condominium, foreign national, and construction to permanent where you have it.
Give a niche example. Placing a self-employed borrower who was declined by a bank, structuring an investor purchase around rental income, or finding a lender for a condominium project that failed agency review are the situations that show real panel knowledge rather than an approval list.
Pricing tools belong in this section. Say which product and pricing engine you use, how you decide on a lock term, and how you handle an extension when a file slips, because lock management is where broker margin quietly disappears.
File quality: pre-underwriting and compliance
Describe how you build a file before submission. Reading tax returns yourself, running income to the specific guideline rather than to an automated finding, checking condominium project eligibility early, and calling the account executive on an unusual scenario before disclosure are all pre-underwriting habits that show up in pull-through.
Compliance is not optional detail here. Disclosure timing after application, redisclosure on a valid changed circumstance, fee tolerance handling and documented borrower contact are the areas an audit inspects. State the discipline plainly.
If you have been through a state examination or an internal audit without findings, say so. Owners take on regulatory exposure when they add an originator, and a clean examination record reduces the perceived risk of hiring you.
Where the business comes from
Name your sources and their share. Real estate agent referrals, past client repeat business, builder relationships, financial planners and certified public accountants, credit unions, and paid internet leads each behave differently and cost differently. A book built on agent partnerships transfers to a new brokerage; a book built on the previous employer's lead spend usually does not.
Quantify the partner base. Twenty-two active referring agents who sent business in the last year is a specific and checkable statement, and it answers the only question a hiring owner really has about a producer.
Add the activities that maintain it. Joint seminars, listing presentation support, preapproval turnaround commitments and post-closing follow-up are the work behind the referral count, and describing them shows the network is maintained rather than inherited.
Mortgage Broker resume summary examples
Newly licensed originator
Newly licensed loan originator with a completed education requirement and a passing examination result, coming from three years of bank branch lending. Familiar with conventional and FHA documentation, income calculation from pay stubs and returns, and preapproval turnaround, seeking a brokerage with mentorship and a broad lender panel.
Producing broker
Licensed mortgage broker funding 9 to 12 loans a month through nineteen wholesale lenders across conventional, FHA, VA and bank statement programs. Holds submission to funding pull-through at 88% by pre-underwriting to the chosen investor guideline, with 70% of volume from repeat agent partners.
Broker owner and team lead
Broker owner producing personally while leading four originators, with a combined annual volume above forty million and a purchase heavy mix through two market cycles. Built the lender panel, the pricing policy and the file intake checklist, and has completed two state examinations without findings.
Work experience bullets: before and after
Before: Originated residential mortgage loans for clients.
After: Funded 9 to 12 loans a month across conventional, FHA, VA and bank statement non-QM products through a panel of nineteen wholesale lenders.
Monthly units, product breadth and panel size describe a producer; the weak version describes a job title.
Before: Worked closely with real estate agents to get referrals.
After: Sourced 70% of annual volume from twenty-two active referring agents, supported by joint first-time buyer seminars and a same-day preapproval commitment.
A counted partner base with the activity that sustains it shows a book that could move with you.
Before: Made sure files were complete before sending to the lender.
After: Pre-underwrote every file against the selected investor guideline, calculating self-employed income from returns before disclosure, and held pull-through from submission to funding at 88%.
The method and the resulting pull-through connect a habit to a number an owner can value.
Before: Found solutions for difficult borrowers.
After: Placed a self-employed borrower declined by two banks into a bank statement program by documenting deposits and structuring reserves, closing within the original contract date.
One concrete placement demonstrates panel knowledge far better than a general claim about solutions.
Before: Followed all lending regulations and disclosure rules.
After: Issued initial disclosures within the required window on every application and redisclosed on valid changed circumstances, completing two state examinations with no findings.
Specific timing behavior plus an examination outcome converts compliance from a claim into a record.
Hard skills
- Residential mortgage origination
- Wholesale lender placement
- Conventional and jumbo products
- FHA and VA lending
- Bank statement and profit and loss programs
- Investor debt service coverage loans
- Self-employed income analysis
- Credit review and tradeline strategy
- Product and pricing engines
- Rate lock and extension management
- Arive and LendingPad
- Encompass
- Disclosure timing and changed circumstance handling
- Referral partner development
Soft skills
- Setting expectations before an application
- Delivering bad news early
- Negotiating with account executives
- Persistence through a stalled file
- Teaching agents what a preapproval means
Certifications worth listing
- Mortgage Loan Originator License (Nationwide Multistate Licensing System and Registry)
- Certified Mortgage Consultant (CMC) (National Association of Mortgage Brokers)
- Certified Residential Mortgage Specialist (CRMS) (National Association of Mortgage Brokers)
- Accredited Mortgage Professional (AMP) (Mortgage Bankers Association)
Mistakes that cost mortgage broker candidates the interview
- Burying the originator identifier and state licenses instead of putting them under your name.
- Reporting annual dollars only, which flatters a high price market and hides how many families you closed.
- Showing one exceptional year and omitting the years around it, which reads as a rate window rather than a pipeline.
- Listing a lender panel by count without naming the product niches you can actually place.
- Leaving out pull-through, the number that tells an owner whether your files create rework.
- Describing referral relationships without counting the partners who sent business in the last year.
- Treating compliance as a values statement instead of stating disclosure behavior and examination outcomes.
Mortgage Broker resume questions
Should a mortgage broker resume show volume in dollars or in units?
Show both, with units first. Units compare cleanly across markets while dollar volume swings with local prices, and a hiring owner uses units to estimate the processing capacity and support your production would require from their operation.
How do I present production from a refinance heavy period?
Label the mix rather than hiding it. State the purchase and refinance split for each year and add what you did to build purchase business as rates moved, since brokers are judged on whether they can produce when the easy volume disappears.
What should I put on the resume if I am newly licensed with no funded loans?
Lead with the license, the completed education hours and the examination result, then translate prior work: bank lending, underwriting support, real estate sales or collections all carry relevant document and credit knowledge. Say clearly that you are seeking a brokerage with mentorship.
Do I need to list every state I am licensed in?
Yes, because many openings exist precisely to cover a state. List them in the header and keep the list current, and note any application in process separately so the reader is not surprised later in the hiring process.
Is it worth naming my wholesale lenders individually?
Naming a few of the largest is fine, but the more useful information is the number of approvals and the product categories they let you place. Owners are trying to learn whether you can find a home for an unusual file, not to audit your approval list.
Related resume examples
- Mortgage Loan Officer Resume example
- Loan Officer Resume example
- Mortgage Processor Resume example
- Mortgage Underwriter Resume example
- Real Estate Agent Resume example
- Real Estate Transaction Coordinator Resume example