Mortgage Underwriter Resume Examples: what gets the call
Write a Mortgage Underwriter Resume That Shows Authority and Accuracy
By Mustafa Tarabya, founder of CVBooster · Published · Updated
Mortgage underwriter resume example, keyword list and writing guide covering signing authority, file volume, agency guidelines, audit results and DU findings.
Sample resumes for a mortgage underwriter
The same mortgage underwriter content laid out in three CVBooster templates, so you can see what the finished document looks like before you write a word.
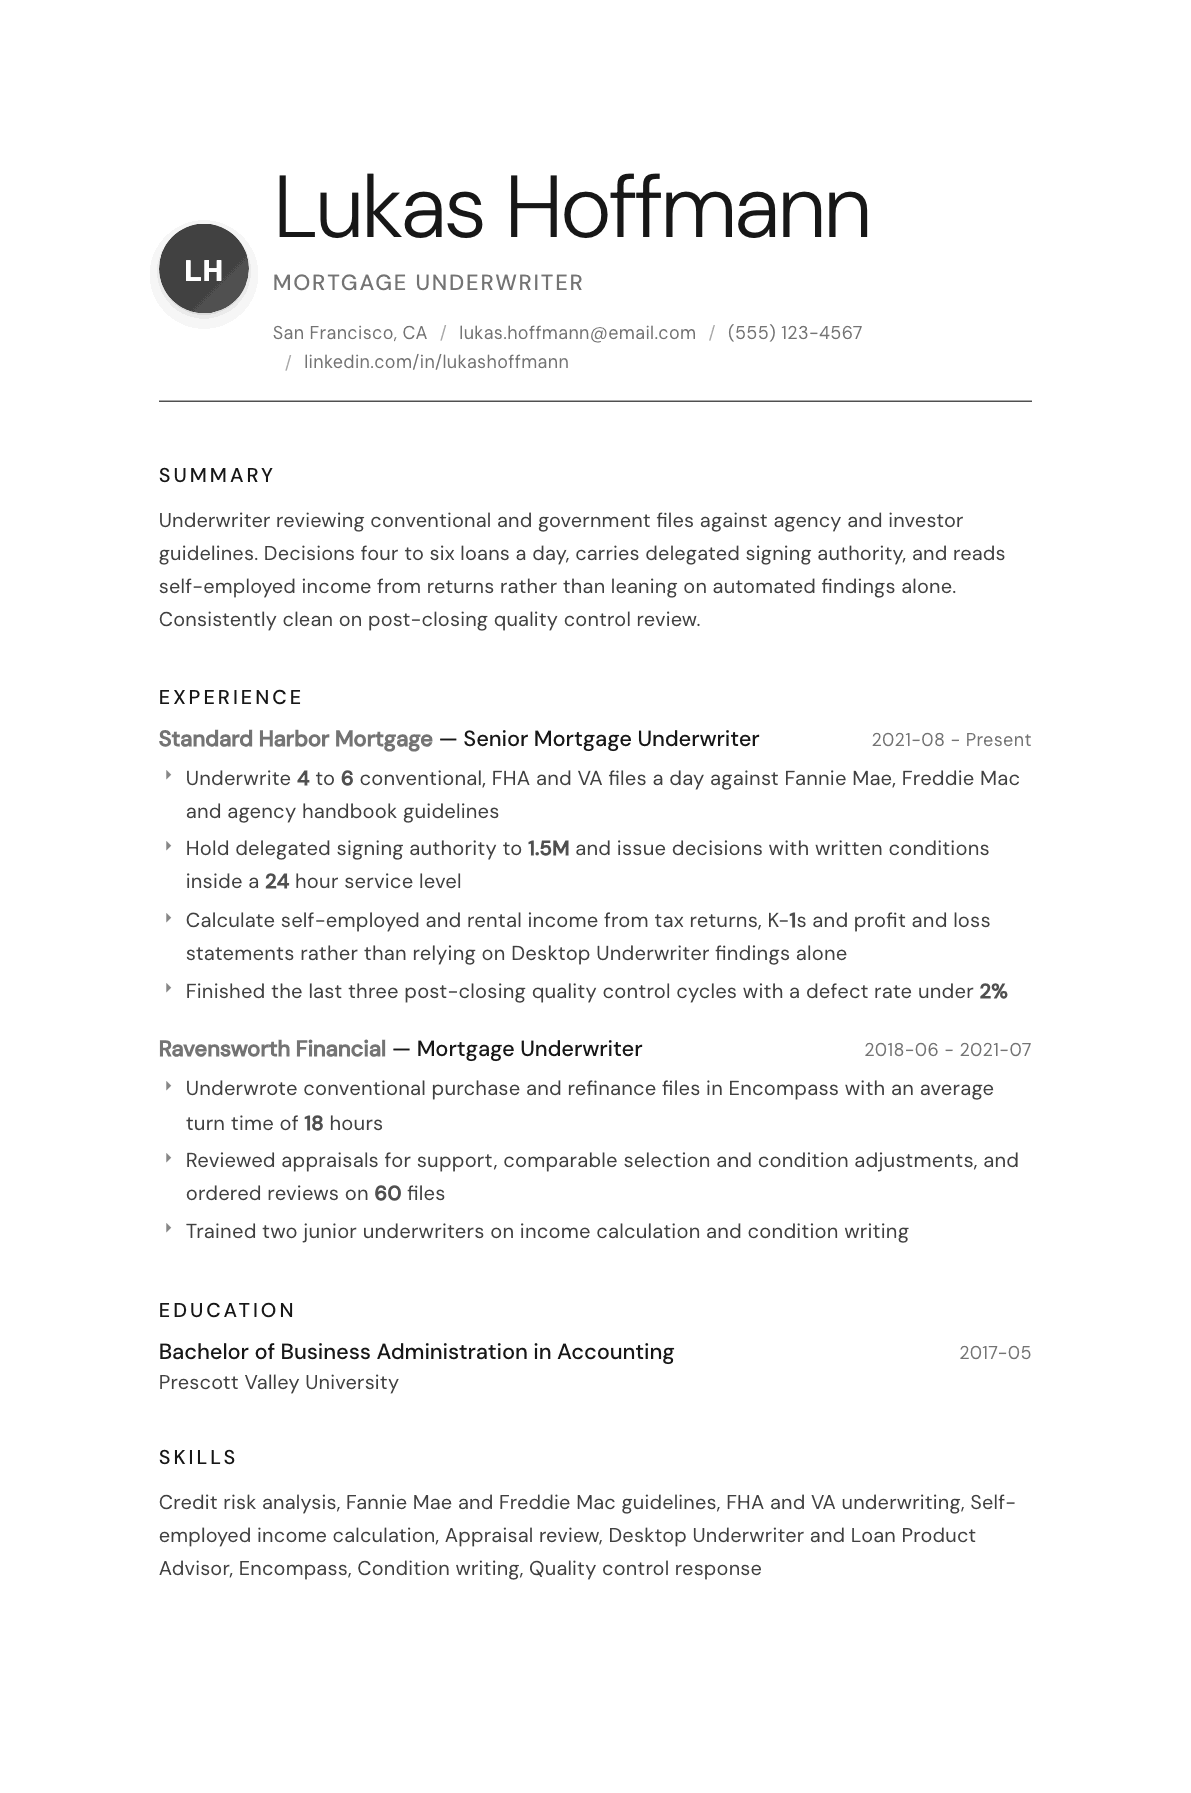
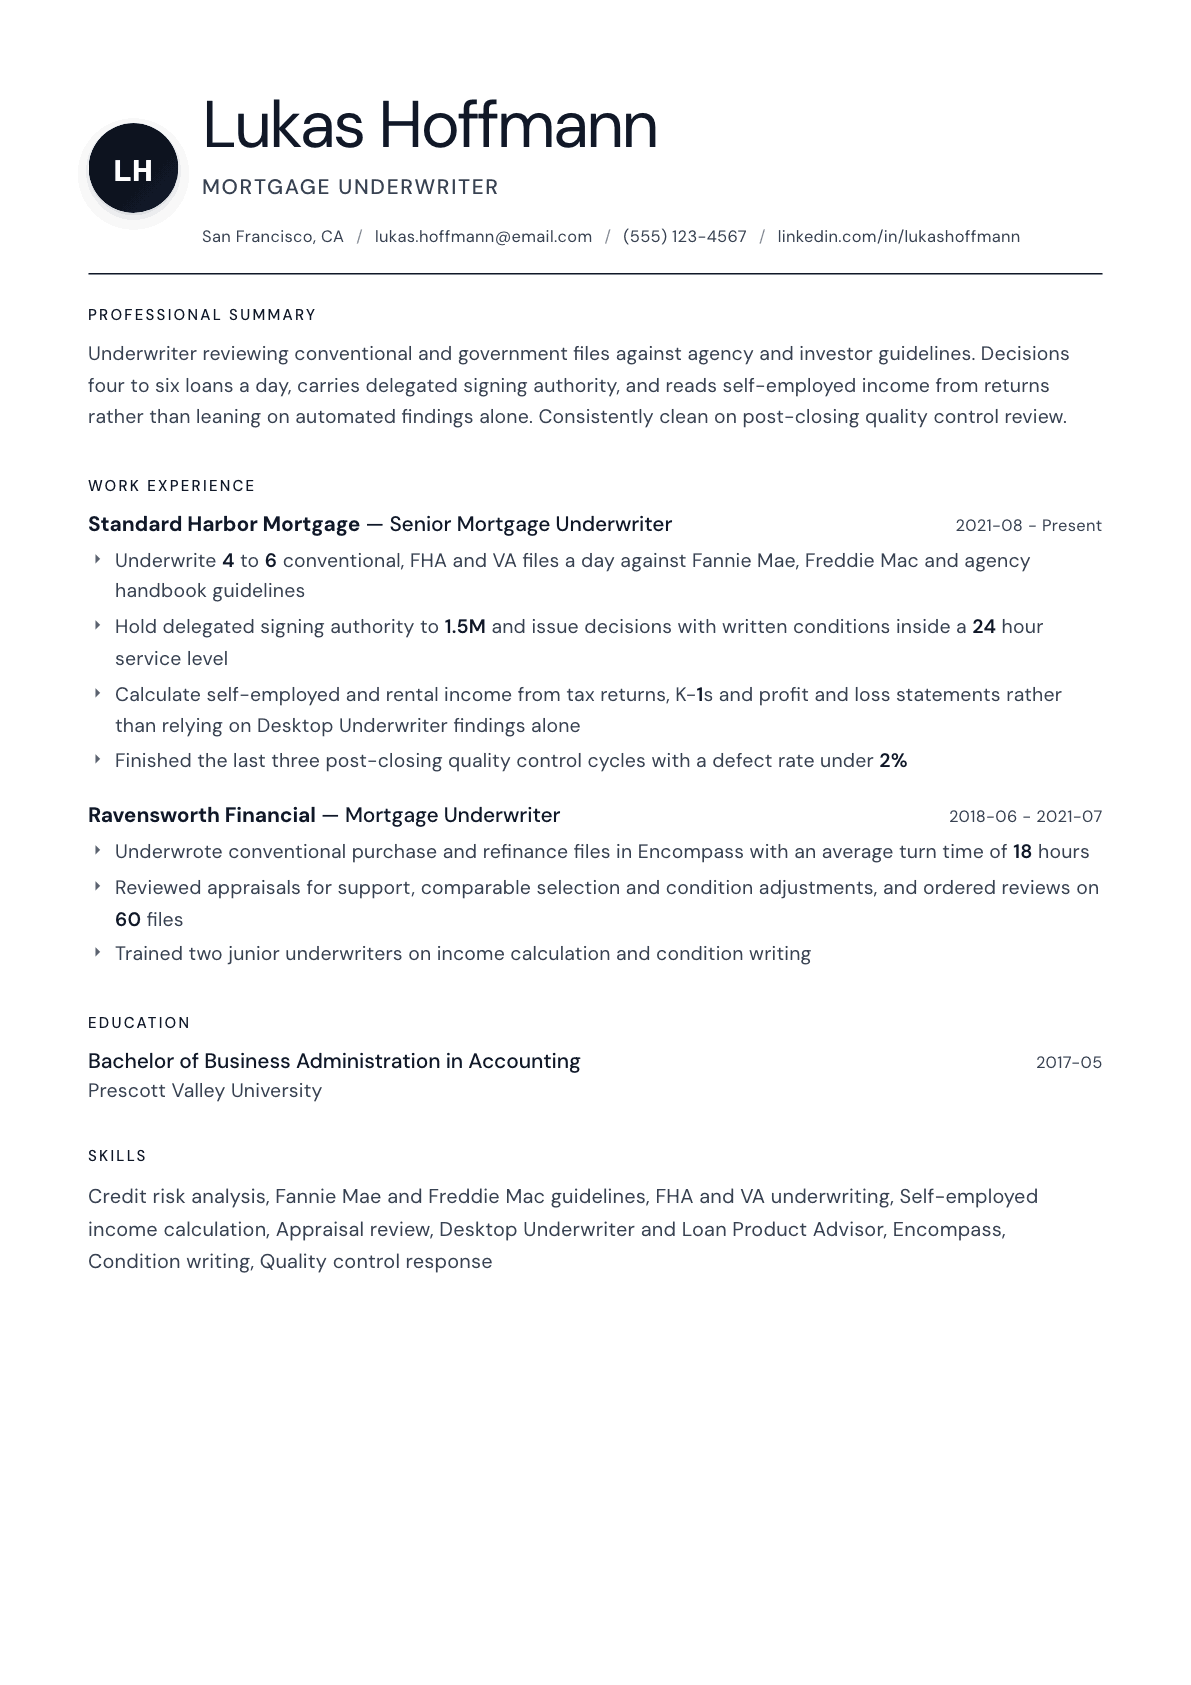
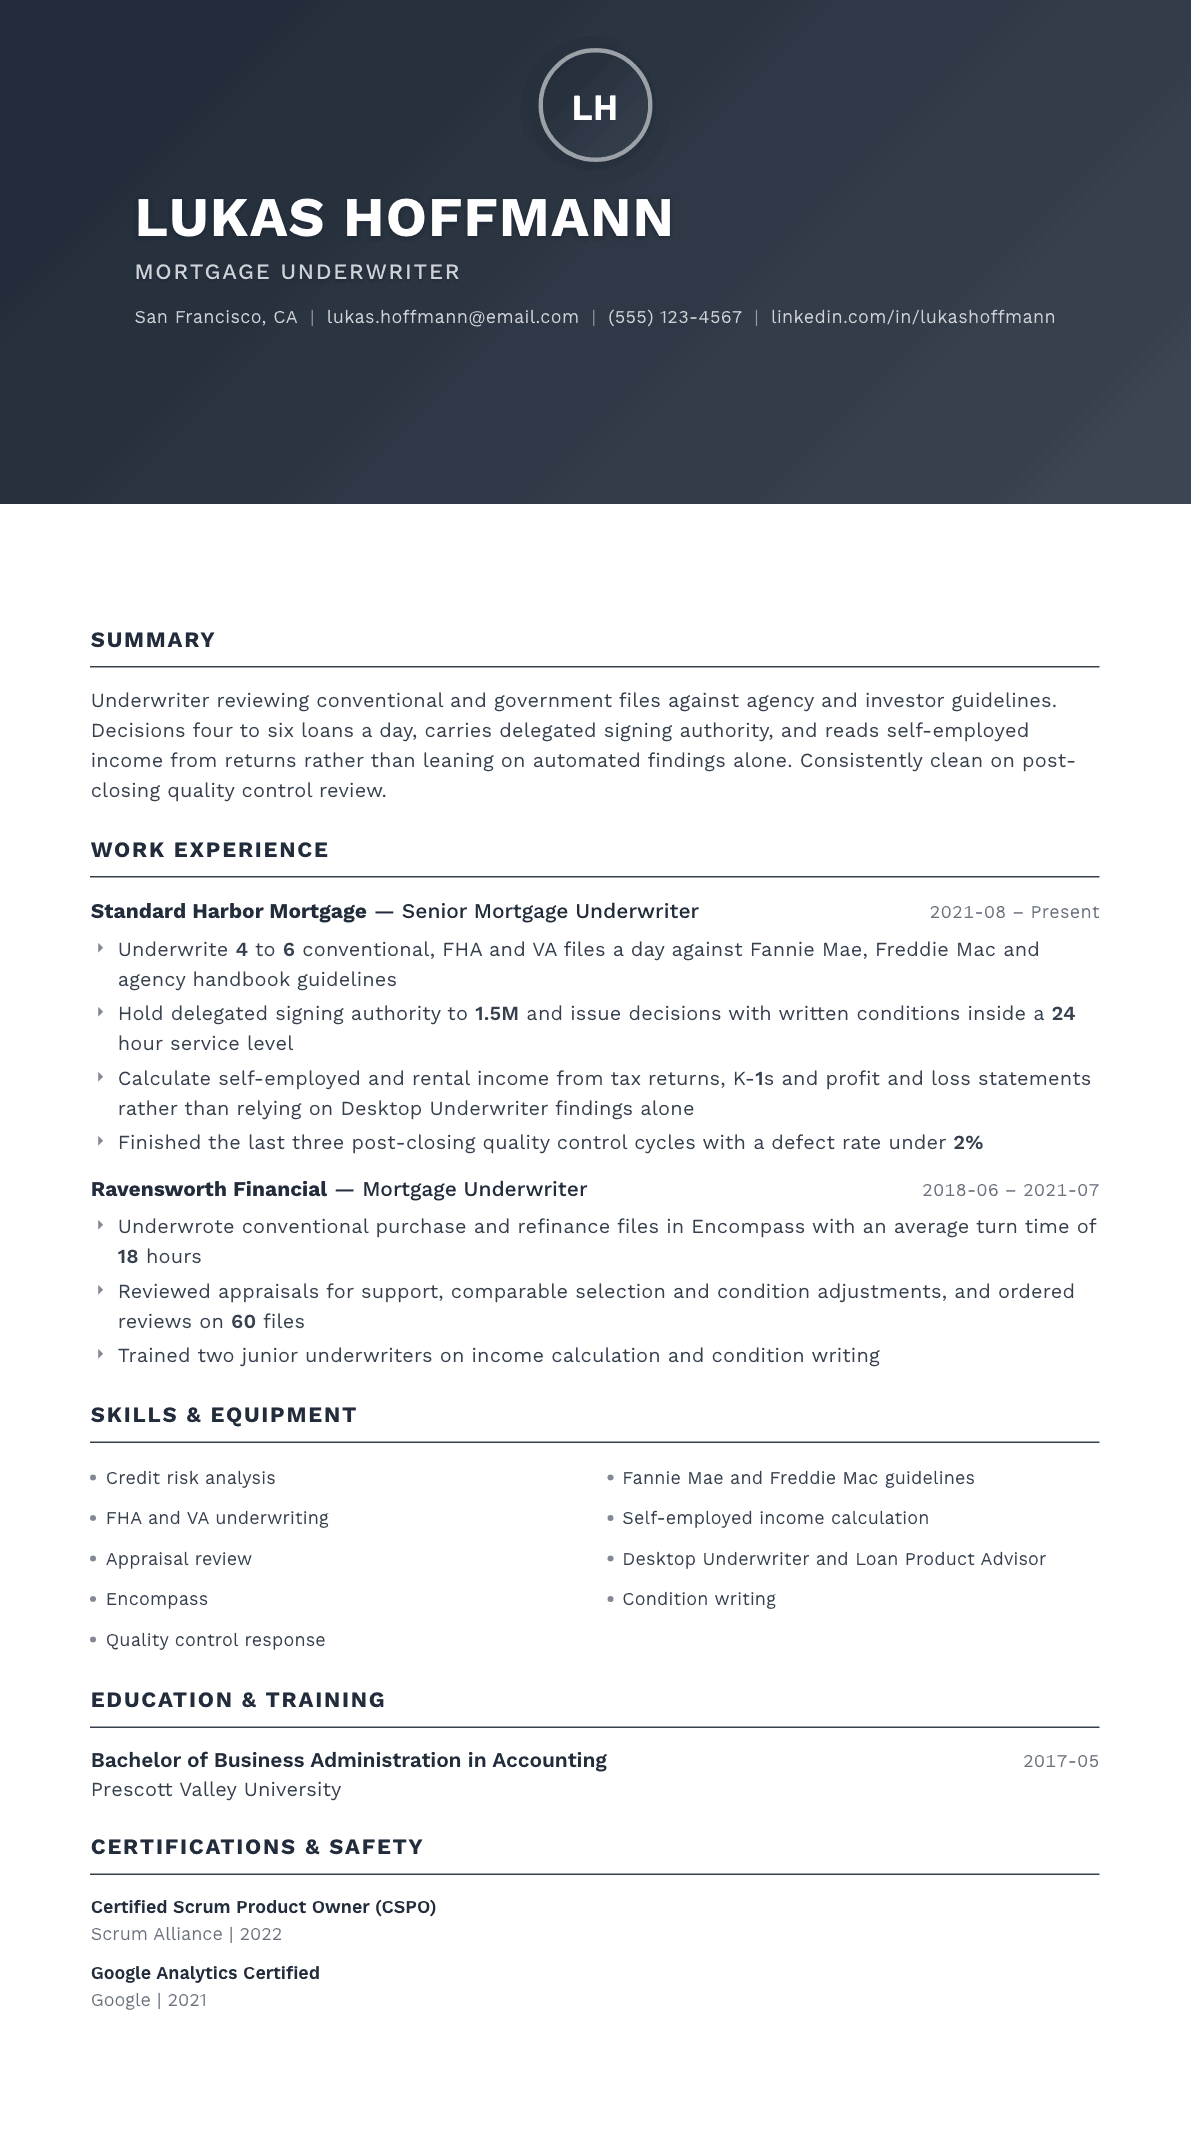
Example Mortgage Underwriter summary
Mortgage underwriter with eight years across conventional and government lending, decisioning four to six files a day with delegated signing authority. Calculates self-employed, rental and variable income from returns and works appraisals for comparable support rather than clearing findings blind. Holds a defect rate under two on the last three quality control cycles. Works Encompass with Desktop Underwriter and Loan Product Advisor.
Skills to list on a Mortgage Underwriter resume
- Conventional loan underwriting
- FHA and VA underwriting
- Fannie Mae Selling Guide application
- Freddie Mac guideline application
- Self-employed income analysis
- Rental and variable income calculation
- Debt to income and reserve analysis
- Credit report and tradeline review
- Appraisal and collateral review
- Desktop Underwriter findings
- Loan Product Advisor
- Encompass and Blend
- Condition writing and clearing
- Fraud and red flag detection
- Post-closing quality control response
What actually gets this resume read
- State your signing authority limit and whether it is delegated or non-delegated, because that defines the level you are hired at.
- Give daily file decision volume and the loan types: conventional, FHA, VA, USDA, jumbo or non-QM.
- Name the automated systems you clear findings in, such as Desktop Underwriter, Loan Product Advisor or Total Scorecard.
- Show your income calculation depth, especially self-employed, rental and variable income, since that is what separates underwriters.
- Report quality control and audit results, because a lender hires on defect rate more than on speed.
- List the guideline sources you work from by name, including agency selling guides and investor overlays.
- Say how fast you turn a file and how you write conditions, since condition quality drives processor rework.
How to write a mortgage underwriter resume
An underwriting manager reads your resume looking for two things that are hard to fake: the authority you were trusted with and the quality of the decisions you made with it. File counts matter, but a fast underwriter with a poor post-closing record costs a lender repurchase exposure, and every manager in this field has lived through that.
The resumes that stall describe the workflow. They say the candidate reviewed loan files, verified documentation and issued approvals, which is true of everyone holding the title and tells the reader nothing about depth. Depth in underwriting shows up in income calculation, collateral judgment and how you write conditions.
This guide walks through signing authority, daily decision volume by product, the income scenarios worth naming, appraisal and collateral review, quality control outcomes, and how to present automated system work without sounding like you only clear findings.
Format: authority and product mix in the top third
One page up to about five years, two after that if you have carried multiple product types or a mentoring role. The reader is comparing candidates on level, so the top third has to answer what you can sign and what you can sign it on.
Underwriting postings are keyword heavy because lenders filter on product and guideline experience. Use the exact phrases the industry uses, including the agency selling guide names and the automated system names, and keep them as plain text.
- Header: name, city and state, phone, email, and any underwriting designation or agency training you have completed.
- Order the page as summary, authority and product mix, experience, guideline expertise, systems, quality record, education.
- Under each role state daily file decisions, product types, whether the role was delegated or non-delegated, and the service level you worked to.
- Add a quality line giving audit or post-closing defect results with the review period they cover.
Authority: delegated, limits and escalation
State your signing limit and whether the authority was delegated by the investor or held internally. An underwriter approving inside delegated authority carries the lender's representation and warranty exposure, which is a materially different job from submitting files for investor review, and managers hire for the specific one they need.
Name what always escalates. Exceptions to guideline, files with layered risk, non-delegated products and anything requiring a variance typically go up regardless of amount, and describing that boundary shows you understand where your decisions end.
If you have granted exceptions, describe the framework rather than the file: compensating factors documented, the approving level, and how the exception was recorded for later audit. That is the language a credit risk manager uses.
Income calculation is where underwriters separate
Salaried borrowers with two pay stubs do not test an underwriter. Name the scenarios that do: self-employed borrowers with a sole proprietorship schedule, partnership and S corporation returns with K-1 distributions and business liquidity questions, rental income from a schedule with depreciation and vacancy treatment, commission and bonus income with a declining trend, restricted stock, and seasonal or contract income.
Say that you calculate rather than accept. An underwriter who works income from returns and worksheets, and who can explain why the automated finding and the manual calculation differ, is worth substantially more than one who takes the system output as the answer.
Add the ratio and reserve work around it. Debt to income under different treatment of student loan payments, reserve requirements by occupancy and property type, and residual income where the product requires it are all specific enough to prove hands-on experience.
Collateral, credit and fraud detection
Appraisal review is a real skill and most resumes skip it. Describe what you check: comparable selection and proximity, adjustment support, condition and quality ratings, market trend indications, and when you order a desk review, a field review or a second appraisal.
Credit analysis should go beyond the score. Recent delinquency patterns, disputed tradelines that need resolution before decision, undisclosed debt found at a soft pull refresh, and derogatory events with seasoning requirements are all part of the decision.
Then red flags. Occupancy misrepresentation, straw buyer patterns, altered documents, employment verification that does not survive a second check, and transactions where the parties are related without disclosure. An underwriter who has caught and documented one of these should say so in a way that shows the process followed, not the drama.
Conditions, turn time and the quality record
Condition writing is an underestimated part of the job. Conditions that are specific, individually satisfiable and written in language a processor and a borrower can act on reduce touches per file. If your average condition count fell or your files came back cleared on the first submission more often, that is a result worth stating.
Give turn time against the service level you were held to, not in isolation. Deciding files inside a twenty-four hour standard while the team standard was forty-eight is a comparison a manager understands immediately.
Close with quality. Post-closing quality control defect rate, investor audit results, repurchase requests received, and any early payment default review you were part of. A clean record with the period stated is the strongest close an underwriting resume can have.
Mortgage Underwriter resume summary examples
Junior underwriter
Junior underwriter with two years reviewing conventional purchase files under a senior signature, calculating salaried and simple self-employed income and clearing prior to document conditions. Completed agency guideline training and works Desktop Underwriter daily, ready for delegated authority on conforming files.
Conventional and government underwriter
Mortgage underwriter decisioning 4 to 6 conventional, FHA and VA files a day against agency and investor guidelines, with delegated signing authority and a 24 hour service level. Calculates self-employed and rental income from returns and reviews appraisals for comparable support before issuing conditions.
Senior underwriter and mentor
Senior underwriter with nine years across conventional, government and jumbo products, holding delegated authority at the highest tier on the team and handling exception requests with documented compensating factors. Trains junior underwriters on income calculation and condition writing, with a defect rate under 2% across three quality cycles.
Work experience bullets: before and after
Before: Reviewed and approved mortgage loan applications.
After: Underwrote 4 to 6 conventional, FHA and VA files a day against Fannie Mae, Freddie Mac and agency handbook guidelines within a 24 hour service level.
Daily volume, product mix, guideline sources and the service standard place you precisely against a job posting.
Before: Calculated borrower income from documentation.
After: Calculated self-employed, partnership and rental income from tax returns, K-1s and profit and loss statements, reconciling manual results against automated findings before issuing a decision.
The income types and the reconciliation habit show depth that a general income statement cannot.
Before: Reviewed appraisals as part of the loan file.
After: Reviewed appraisals for comparable selection, adjustment support and condition ratings, ordering desk or field reviews on 60 files where market data did not support the reported value.
Naming the review criteria and the number of escalations proves collateral judgment rather than a checkbox.
Before: Wrote conditions for the processing team to clear.
After: Wrote individually satisfiable conditions with the exact document and guideline citation, cutting average conditions per file from nine to five and reducing second submissions.
It ties condition writing style to a measured reduction in rework, which is what an underwriting manager buys.
Before: Maintained good quality on the loans I underwrote.
After: Finished the last three post-closing quality control cycles with a defect rate under 2% and no repurchase requests on files decisioned under delegated authority.
A defect rate with a stated period and no repurchases is the credible version of a quality claim.
Hard skills
- Conventional loan underwriting
- FHA and VA underwriting
- Fannie Mae Selling Guide application
- Freddie Mac guideline application
- Jumbo and portfolio guidelines
- Self-employed and partnership income analysis
- Rental and variable income calculation
- Debt to income and reserve analysis
- Credit report and tradeline review
- Appraisal and collateral review
- Desktop Underwriter and Loan Product Advisor
- Encompass and Blend
- Condition writing and exception documentation
- Fraud and red flag detection
Soft skills
- Decisiveness with incomplete files
- Explaining a denial without defensiveness
- Resisting pressure from production
- Written clarity in conditions
- Consistency across a long day of files
Certifications worth listing
- Certified Mortgage Banker (CMB) (Mortgage Bankers Association)
- Accredited Mortgage Professional (AMP) (Mortgage Bankers Association)
- Certified Master Mortgage Underwriter (CMMU) (National Association of Mortgage Underwriters)
- Direct Endorsement Underwriter Authority (Federal Housing Administration)
Mistakes that cost mortgage underwriter candidates the interview
- Leaving out the signing limit and whether authority was delegated, which is the first thing a manager needs to know.
- Describing file review generically instead of naming the income scenarios you can actually calculate.
- Skipping appraisal and collateral review, which many underwriters treat as someone else's job until it is not.
- Reporting turn time without the service level standard it should be measured against.
- Omitting quality control results, the only evidence that speed did not come at the cost of defects.
- Talking about automated findings as though clearing them is the same as underwriting the file.
- Failing to separate conventional, government and non-agency experience when lenders hire for one of them.
Mortgage Underwriter resume questions
How important is signing authority on a mortgage underwriter resume?
It is the clearest level indicator you have. State the limit, whether the authority was delegated, and any product it did not cover. Two candidates with identical file counts can sit two pay grades apart depending on what they were permitted to sign without review.
Should I list the number of files I underwrite per day or per month?
Per day, since that is how underwriting capacity is planned and how service levels are set. Add the product mix in the same sentence, because six conforming refinances and six self-employed jumbo purchases are not the same day of work.
How do I show underwriting skill if my quality results were never shared with me?
Use what you can substantiate: your condition clearing rate, resubmission frequency, any investor audit you supported, and the complexity of files routed to you. Being the underwriter your manager assigns difficult income scenarios to is itself a quality signal worth stating.
Does government underwriting experience transfer to conventional roles?
Largely yes, because credit, income and collateral analysis are common, but the guideline sources and documentation requirements differ. Say which handbooks you have worked from and whether you held direct endorsement authority, then note the conventional volume you have carried alongside it.
How do I handle a resume gap from a lending downturn?
State it directly with dates and what you did, whether contract underwriting, quality control review, servicing or study toward a designation. Underwriting headcount moves with volume, and managers read a cycle related gap very differently from one left unexplained.
Related resume examples
- Underwriter Resume example
- Mortgage Loan Officer Resume example
- Mortgage Processor Resume example
- Loan Processor Resume example
- Insurance Underwriter Resume example
- Mortgage Broker Resume example